

What Is In-House Financing and How Does It Work for Modern Businesses?

In-house financing lets businesses act as direct lenders to their customers. Rather than sending buyers to banks or third-party finance companies, the business extends credit itself and manages the entire loan lifecycle.
This model is growing fast in the United States and Canada. Alternative lending reached $255 billion in the U.S. in 2023 and is projected to hit $378 billion by 2028. More businesses are choosing to finance their own sales because third-party fees eat into margins and slow down the sales process.
In-house financing works best for companies with high-ticket products or services. HVAC contractors, auto dealers, medical practices, solar installers, and home renovation businesses see strong results. These operations typically have average transaction values above $5,000 and enough volume to justify the operational overhead.
The catch is that operational discipline matters more than most businesses expect. Weak underwriting loses money. Manual servicing doesn’t scale. Poor collections destroy margins. Companies that succeed treat in-house financing as a lending operation, not just a sales tool.
Market Context: Why In-House Financing Is Growing in the U.S. and Canada
United States Market Dynamics
The U.S. alternative lending market reached $255 billion in 2023. Projections show it hitting $378 billion by 2028, growing at roughly 7.4% annually. This growth reflects a structural shift in how businesses and consumers access credit.
The Federal Reserve’s Small Business Credit Survey found that 37% of small businesses applied for financing in the past year. About one-third of those applications went to non-bank lenders rather than traditional banks. Traditional banks still dominate business lending, but their market share is declining.
Point-of-sale financing shows the strongest growth. Shopify Capital originated approximately $3 billion in merchant financing in 2024. Buy now, pay later services now account for roughly 6% of U.S. e-commerce transactions. Merchants using BNPL report average order value increases of 20-40%.
These numbers matter because they show customer demand for flexible payment options. Businesses that don’t offer financing lose sales to competitors that do. The infrastructure to provide financing in-house has become more accessible through embedded finance platforms.
Canada Market Dynamics
Canada’s small business financing landscape shows similar patterns with some important differences. The 2023 SME financing data shows that 49.3% of Canadian SMEs requested financing. Total SME debt demand reached $94 billion.
Only 2.2% of that demand went to online alternative lenders. This low penetration represents opportunity. The alternative lending market in Canada is forecast to exceed $30 billion in the next few years as businesses look beyond traditional banks.
Canadian SMEs pay higher interest rate spreads compared to the OECD average. This pricing gap makes in-house financing more competitive. Businesses that can offer financing at rates below typical alternative lender pricing gain a significant advantage.
The regulatory environment in Canada is more fragmented than in the U.S. Provincial consumer protection laws vary. Businesses expanding in-house financing across provinces need legal guidance on licensing requirements and disclosure obligations.
Strategic Implications
These market trends point to three operational realities:
- Customer expectations have shifted. Buyers expect payment flexibility at point of sale.
- Traditional financing partners capture margin. Third-party lenders typically charge 2-6% of transaction value.
- Technology has lowered barriers. Cloud-based lending platforms make in-house financing operationally feasible for mid-market businesses.
Businesses that move early gain competitive advantage. But success requires treating this as a lending operation with proper risk management, not just a sales enhancement.
What In-House Financing Means
In-house financing is when a business extends credit directly to its customers for purchases of its own products or services. The business acts as both seller and lender.
This differs from third-party financing where an external lender provides the capital and assumes the credit risk. With third-party arrangements, the business receives full payment upfront while the customer repays the lender.
In-house financing also differs from buy now, pay later services. BNPL providers are third parties that integrate at checkout. The merchant gets paid immediately. The BNPL provider manages collections and bears the risk.
With in-house financing, the business keeps both the risk and the reward. No third party takes a cut of the transaction. The business sets all terms, approves all applicants, and manages all servicing. This control comes with full exposure to defaults and operational complexity.
Some larger businesses create captive finance companies as separate legal entities. The CFC is owned by the parent company but operates independently. This structure provides some risk isolation and can offer tax advantages. Small to mid-sized businesses typically use direct on-balance-sheet financing.
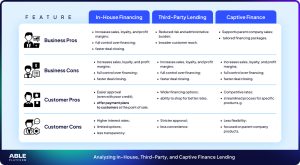
How In-House Financing Works
In-house financing programs require six operational components working together:
Capital Structure
The business needs available capital to fund customer loans. This capital comes from operating cash flow, credit lines, or dedicated lending facilities. Most businesses underestimate capital requirements by 30-50% in their first year.
A $10,000 average ticket with 30 financed sales per month requires $300,000 in outstanding receivables at steady state. Add working capital for operations and a reserve for defaults. Most programs need $400,000-500,000 in available funding to operate smoothly.
Businesses typically start with revolving credit facilities or working capital loans. As portfolios grow, some businesses securitize their receivables or establish warehouse lines. The funding structure depends on scale and access to capital markets.
Credit Policy
Credit policy defines who qualifies for financing and at what terms. This policy balances acceptance rates with default risk. Too tight and you lose sales. Too loose and you lose money.
Most in-house programs segment customers into tiers. Prime customers get the best rates with low down payments. Near-prime customers pay higher rates or larger down payments. Subprime customers might require 30-50% down or cosigners.
The policy needs to specify maximum loan amounts, term limits, rate floors and ceilings, and required down payments by tier. It should define automatic approval thresholds and escalation requirements for exceptions.
Underwriting Workflow
Underwriting evaluates each application against credit policy. Basic programs pull credit bureau data and apply simple scorecards. More sophisticated operations incorporate bank account analysis, income verification, and alternative data.
Fast underwriting matters. Customers make buying decisions in real time. Applications that take 48 hours to approve lose to competitors with instant decisions. Most successful programs target decisions within minutes for straightforward applications.
Automated decision engines handle 70-80% of applications with no human review. Edge cases and exceptions go to underwriters. The automation threshold should rise as the business gains experience with its customer base.
Servicing Lifecycle
Servicing includes payment processing, account management, customer communications, and recordkeeping. This operation runs daily throughout the loan term.
Payment processing needs to handle ACH, credit cards, and paper checks. Automatic payment enrollment rates directly impact delinquency. Programs with 80%+ autopay enrollment see significantly lower default rates.
Account management tracks payment history, applies payments correctly, calculates interest, generates statements, and maintains compliance documentation. Manual servicing on spreadsheets breaks down past 100-150 active loans.
Collections Strategy
Collections start before delinquency. Pre-due reminders reduce late payments by 15-25%. Early intervention on missed payments matters more than aggressive collection later.
Most programs use a tiered approach. Days 1-15 past due trigger automated reminders and outbound calls. Days 16-30 escalate to skip tracing and payment plan negotiations. After 30 days, accounts move to formal collections with potential legal action.
Recovery rates drop sharply after 60 days delinquent. Businesses that wait too long to escalate collection efforts see recovery rates below 20%. Aggressive early intervention recovers 60-70% of delinquent balances.
Portfolio Monitoring
Ongoing portfolio monitoring identifies problems early. Key metrics include delinquency rates by vintage, loss rates by customer segment, and portfolio yield versus cost of funds.
Monthly reporting should track origination volume, outstanding balance, weighted average coupon, delinquency buckets, charge-offs, and net portfolio yield. These metrics drive underwriting adjustments and pricing changes.
Businesses should stress test their portfolios quarterly. What happens if delinquencies double? What if the economy enters recession? Understanding portfolio sensitivity to macroeconomic changes prevents catastrophic losses.
Why More Businesses Are Switching to In-House Financing
In-house customer financing is one of the rising trends in loan origination software. Here are the main reasons for its popularity:
- Customer demand for flexibility. Clients often postpone expensive purchases because they don’t have the full sum of money to make the payment upfront. Thus, in-house financing can make many services and products more accessible and drive sales here and now. For instance, the availability of customer financing solutions for dental practices can help clients use dental services now and pay for them in instalments over several months or years.
- Sales growth. In-house financing is a powerful tool that can increase the conversion rate by making the purchase affordable at the moment. Thus, businesses obtain more permanent clients by giving them flexible and accessible financing options.
- Control over customer experience. By delegating HVAC financing or medical financing to third-party lenders, businesses lose a vital portion of their revenue and control over the loan repayment process. In-house financing solves this issue by empowering each business to offer unique financing terms and offers, improve customer experience, and control the entire loan lifecycle.
- Removal of third parties. External lenders may be solid financing partners, but they charge additional fees for their services, which may become an extra burden for businesses and clients. Thus, by launching in-house financing software and opening an internal line of credit to clients, any business can reduce the cost of financing for all participants.
These benefits drive more and more businesses to assume a more active role in financing their clients’ purchases and become a direct financing partner with full control over money flows.
Who Is In-House Financing For?
The in-house financing solution offers powerful benefits across many industries by enhancing customer trust, boosting sales, and increasing the accessibility of high-ticket products and services. The sectors that can benefit the most from its implementation include:
- HVAC services. HVAC system installation and repair is a very costly project that not every homeowner can afford. In-house financing plans at HVAC companies empower people to enjoy HVAC setup or restoration at the moment they need it, instead of running into emergency situations.
- Renewable energy providers. The installation of solar panels comes with huge upfront costs, which are later offset by renewable energy generation. To make this solution more affordable, companies offer solar financing options that allow households to enjoy low-cost energy. This solution also boosts the transition to clean energy, thus helping states meet the modern carbon footprint targets.
- Equipment sales. Heavy-duty construction, agricultural, and logistical equipment is usually very expensive, but it’s integral to the operation of major companies in these sectors. Instead of investing a lump sum into equipment purchases, business owners can distribute the repayment for a convenient period and avoid a strain on their finances.
- Medical and dental services. Many healthcare and dental procedures are financially unreachable for clients. By accessing dental financing tools, patients can realize their dreams and perform therapeutic and reconstructive procedures at a convenient price.
- Automotive dealers. The implementation of auto dealership finance software is a sure way to boost car sales in the stagnating market. Few households can afford to pay the full cost of a vehicle upfront today, so car financing enjoys steady demand. In-house auto finance software helps dealers navigate the entire process. In-house financing is usually much more affordable than traditional bank loans; besides, it helps auto dealers establish long-term relationships with clients and retain them to use additional services for car maintenance, insurance, and the like.
- Healthcare providers. Countries with private medical care often offer limited treatment coverage for patients beyond the minimal insurance plan. Thus, in-house financing for costly medical procedures and interventions can ease people’s access to high-quality services.
- Home renovation services. The majority of home renovation tasks, such as kitchen renovation or roof repairs, come with a high price tag that a household can rarely afford to pay in full. The availability of in-house financing options in this industry also makes renovation more affordable and allows households to complete renovation without delays.
- Education and training. Reputable educational institutions often charge lots of money for their courses, while students may have limited access to state aid, grants, and loans. Should it be a valid reason to abandon a dream of receiving a prestigious degree? Here’s when in-house educational financing comes into play. Colleges and universities that offer instalment-based tuition plans enjoy greater student enrolment and make high-quality education more accessible.
Businesses in each of these industries can employ in-house financing as a strategic business growth tool. This solution removes the most significant financial barrier to making a purchase, and the provision of flexible repayment terms builds long-term customer loyalty and trust. Thus, companies with high upfront costs of services and products can scale and boost sales via seamless financing solutions.
Why Many In-House Financing Programs Fail
Most in-house financing programs that fail share common mistakes. Understanding these failure modes helps businesses avoid them.
Underestimating Capital Requirements
Businesses calculate initial capital needs based on expected monthly originations. They forget about the ramp period. New programs take 6-12 months to reach steady-state volume.
During ramp-up, the business funds new loans while old loans pay down slowly. This J-curve creates maximum capital demand right when the program is proving itself. Businesses that don’t plan for this run out of funding before reaching profitability.
A realistic capital plan includes 18 months of origination capacity plus a 15-20% reserve for defaults. Most businesses need 2-3x more capital than their initial projections suggest.
Weak Risk Segmentation
Many programs use a one-size-fits-all approach. Everyone gets the same rate and term regardless of credit profile. This approach either loses good customers to competitors with better pricing or loses money on bad credit risks.
Effective programs use at least three tiers. Each tier has distinct pricing, down payment requirements, and approval criteria. This segmentation lets the business compete on price for prime customers while protecting margin on riskier credits.
Without segmentation, businesses also lack data to refine underwriting. You can’t improve what you don’t measure. Segmented portfolios show which credit characteristics predict performance.
No Portfolio Monitoring
Some businesses originate loans and then ignore portfolio performance until losses mount. By the time they notice a problem, hundreds of bad loans are already on the books.
Portfolio monitoring should be monthly at minimum. Track delinquency rates, charge-off rates, and early payment default rates. Compare actual performance to underwriting projections.
Early warning signals include rising delinquency in recent vintages, increasing exception approvals, or declining down payment percentages. These indicators predict future losses 3-6 months ahead.
Manual Servicing
Spreadsheets work for the first 50 loans. After that, manual processes create errors, missed payments, and compliance problems. Businesses underestimate the operational burden of loan servicing.
A 200-loan portfolio generates roughly 2,400 payment transactions per year. Add customer service calls, payment plan modifications, payoff quotes, and collection activities. One person can handle maybe 300-500 loans before drowning in administrative work.
Businesses that scale on spreadsheets eventually experience catastrophic failures. Lost payments, incorrect balances, missed collection opportunities, and regulatory violations. The cost of fixing these problems exceeds the cost of proper systems from the start.
Poor Collections Strategy
Many businesses view collections as confrontational and delay action. They hope customers will self-cure. This hope is expensive.
Delinquent accounts that receive no contact in the first 15 days have default rates 3x higher than accounts with proactive outreach. Waiting 30 days to start collections cuts recovery rates in half.
Successful programs treat collections as customer service. Early contact, flexible payment plans, and respectful communication recover more money with less friction. Aggressive late-stage collection tactics should be the last resort, not the strategy.
Digitization of Customer Assessment and Decision-Making
Digitization of lending and customer-centricity can ideally complement each other. By leveraging digital software solutions, in-house financiers can assess their customers in real-time with no loss of time.
Customer creditworthiness is measured accurately and fast according to the predefined parameters. Quick and comprehensive customer credit approval allows retailers to offer the best loan conditions to borrowers while staying safe from default probability.
Below, you can see examples of an in-house financing software system. We’d like to share some screenshots of ABLE Platform (which is also suitable as installment loan software) with you.
Figure 1 shows how the solution builds customer scorecards.
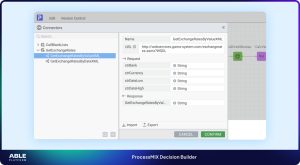
Figure 1. Scorecard builder.
In-house lenders can define a wide range of parameters in it for a more thorough customer analysis.
In-house financing software should enable lenders to build scorecards of any complexity on the basis of Machine Learning models and support the following features:
- An unlimited number of scorecards and model versions.
- ML model supports as separate components and as Python scripts.
- Import of any models supported by the PMML standard.
- Dual-scorecard and multi-scorecard matrices and models.
Acquiring customer data is becoming a vital condition for effective lending. In Figure 2, there’s an application decision builder window. It allows lenders to make loan decisions on the basis of various methods and data sources.
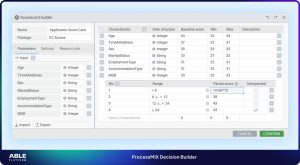
Figure 2. Application decision builder.
To ensure a 360-degree view of a customer for accurate application decisions, a digital solution should have the following functions:
- Application data enrichment from internal and external data sources.
- Data enrichment calls directly from the decision flow.
- Risk-based pricing, LTV-based pricing.
- Behavior-based and event-based pricing.
Digital in-house financing software embraces a wide variety of functions and features. Very often, it’s hard to select the ones you need without consulting experts. Get in touch with our team to get a free consultation on that matter.
Ways to Implement In-House Financing
So, you’re probably looking into in-house financing as a method for revenue and sales growth. In this case, you may choose from several options on how to start a lending business within your existing business infrastructure:
- On-balance-sheet loans. Under this option, you offer financing to clients directly from your company’s balance sheet and record these transactions in your financial statements.
- Captive finance companies. CFCs operate as separate legal entities, handling financing for the parent company’s customer base.
- White-label lending platforms. Platforms like ABLE™ can support both on-balance-sheet and CFC-facilitated financing via a customizable, embedded finance platform.
The choice of the most suitable option largely depends on where you currently are as a business, as each of the methods comes with pros and cons that may put an additional burden on your budget and operations. The best way to go is as follows:
- Startups at the early stage of development may enjoy the simplicity of small-scale, on-balance-sheet loans.
- Mid-sized companies in the active growth phase can benefit from customer financing software, which automates processes from start to finish and enables frictionless scaling.
- Mature enterprises may try white-label loan origination software or partner with a captive finance company to distribute risk and enjoy unlimited scalability.
Each of these paths promises flexibility in payments and reduces the cost of financing solutions in a variety of businesses. However, you should double-check the need for licensing; legal experts should give a clear recommendation on whether you can or can’t offer financing without a license for lending activities.
When In-House Financing Makes Strategic Sense
In-house financing isn’t right for every business. Use this decision framework to evaluate fit:
Business Size & Volume
Companies need minimum scale to justify operational overhead. The breakeven threshold is roughly 100-150 financed transactions annually.
Below that volume, third-party financing makes more sense. The operational burden exceeds the economic benefit. Above that threshold, in-house economics improve rapidly.
Very large operations (1,000+ annual financings) see the strongest returns. These businesses can invest in sophisticated infrastructure and achieve institutional-quality portfolio performance.
Average Ticket Size
Higher ticket prices generate more interest income per loan, which covers fixed servicing costs. Loans below $5,000 rarely justify in-house financing.
The sweet spot is $8,000-$50,000 per transaction. This range provides meaningful interest income while keeping default exposure manageable.
Very high tickets ($100,000+) require sophisticated underwriting and may need secured lending structures. These programs work but demand more expertise.
Customer Base Characteristics
In-house financing works best when customers have financing needs but reasonable credit profiles. If your customer base is primarily prime credit, they can access bank financing easily.
The target is near-prime to mid-prime customers (FICO 620-720). These customers need financing but can’t get competitive rates from banks. Your in-house offering provides real value.
If your customer base is predominantly subprime, expect higher default rates and adjust pricing accordingly. Some businesses succeed in this space, but risk management becomes critical.
Access to Capital
In-house financing requires significant capital deployment. Businesses without access to credit facilities or investment capital can’t fund a lending program.
Banks typically require 18-24 months of operating history and strong financial performance to extend lending facilities. Newer businesses may need alternative capital sources.
Cost of capital matters. If your funding costs exceed 12%, the economics get challenging. Prime borrowers won’t accept rates high enough to cover your costs.
Competitive Positioning
In-house financing creates competitive advantage when competitors don’t offer it or when their offerings have limitations.
If all competitors use the same third-party provider, differentiation is limited. In-house financing lets you offer better rates, faster approvals, and more flexible terms.
The financing option also changes the sales conversation. Instead of debating price, you’re discussing payment options. This shift improves close rates.
Technology Considerations
In-house financing requires proper technology infrastructure. Spreadsheets don’t scale and create unacceptable risk.
Why Spreadsheets Fail
Excel can track 50 loans. Beyond that, manual processes break down. Payment application errors compound. Missed collection opportunities cost money. Compliance documentation gaps create legal exposure.
The failure mode isn’t obvious until it’s catastrophic. Everything seems fine until an audit reveals missing records or a customer lawsuit exposes tracking errors.
Spreadsheet-based servicing also can’t produce required regulatory reports. Many jurisdictions require specific data formats and documentation. Manual processes can’t meet these requirements reliably.
Core Technology Requirements
Loan origination software handles application intake, credit decisioning, document generation, and funding. This system needs to integrate with credit bureaus and bank verification services.
Loan management software tracks payment schedules, processes payments, generates statements, and maintains transaction history. It should handle automatic payment processing and payment plan modifications.
Collections management tools track delinquent accounts, schedule outreach activities, document collection efforts, and report recovery rates. Integration with phone systems and email platforms improves efficiency.
Portfolio analytics provide insight into program performance. Track origination trends, delinquency rates, loss rates, and portfolio yield. Compare actual performance to projections.
Build vs. Buy Decision
Most businesses should buy software rather than building custom systems. Purpose-built lending platforms include essential compliance features and proven workflows.
Building custom systems makes sense only for very large operations with unique requirements. The development cost typically exceeds $500,000 and requires ongoing maintenance.
Cloud-based lending platforms offer good alternatives. Monthly costs range from $500-$2,000 depending on volume. These platforms include all core functionality and regular updates.
Integration Requirements
Lending software needs to integrate with your existing business systems. Key integrations include CRM platforms, accounting software, payment processors, and customer communication tools.
API-based integrations work best. They allow data to flow automatically between systems without manual export/import. This automation reduces errors and improves operational efficiency.
Plan integration work carefully. Poor integrations create manual workarounds that defeat the purpose of automation. Budget 15-20% of software costs for integration work.
Avoiding Product Pitch Mentality
Many lending technology vendors oversell their capabilities. Evaluate platforms based on specific functional requirements, not marketing claims.
Request demonstrations using your actual use cases. Test the workflow with realistic scenarios. Check references from similar businesses.
Total cost of ownership includes software fees, implementation costs, training time, and ongoing support. The cheapest platform often has the highest total cost.
Steps to Implement In-House Financing
Once you start to implement the in-house financing software, you should follow a well-planned, step-by-step algorithm to meet customer needs and retain full control over financing operations. Here is the implementation process we use at ABLE™:
- Analyze your sales stats. First, you need to understand whether in-house financing can boost your sales and customer retention rates. This is possible by looking into your customer data to see whether some clients drop their purchasing decisions because of insufficient liquidity, not because they don’t need your products or services.
- Assess the regulatory environment. Next, you should check whether you can provide financing without a license or authorization, or need to apply for one before opening this service option to clients. As a rule, you don’t need a license if you offer installment payments as an extra service option and don’t promote in-house lending as a separate service. You should also stay in line with consumer lending regulations, such as full loan data disclosure and interest rate caps.
- Develop a creditworthiness evaluation tool. Depending on your business type and sales size, you should establish clear criteria for assessing the applicant’s creditworthiness. This process requires a proper balance between the protection of your financial interests and the prevention of bad loans on the one hand, and making financing accessible to clients on the other hand.
- Enable fully digitized application and approval channels. To simplify access to in-house financing, you need to enable loan applications and approvals online, which is possible with the help of digital documentation arrangements.
- Install a loan servicing system. Set up the full-cycle loan management system that will streamline loan-related operations for you and your clients.
Offer in-house financing options to customers. Integrate information about in-house financing into all channels of your interaction with clients so that they may learn about this option and study all the terms.
This step-by-step approach will ensure that your clients can access flexible and convenient financing services using a smooth, frictionless system.
Conclusion
As you can see, in-house financing is a promising step for many businesses, from point-of-sale financing to HVAC and automotive sectors. It can help you build loyalty, boost sales, and make purchases of costly products and services more affordable for your customers. Direct lending removes the need for third-party lenders and frees you and your customers from costly fees and loan add-ons. Thus, with a well-thought-out strategy and robust, flexible loan management software like that of ABLE Platform™, you’re sure to attain greater business efficiency and profitability.
Frequently Asked Questions About In-House Financing
